An equity dilution model shows what you will own after each funding round, once new investors, option pools and convertible instruments have all been counted. The core maths is short: work out the post-money valuation, give the investor their share, then recalculate every existing holder on a fully diluted share count. The judgement sits in the inputs, especially the option pool and any SAFEs or convertible notes. This guide builds the model step by step with a worked example in pounds, and flags where a UK company has legal steps to complete as well.
TL;DR
- Dilution cuts your percentage, not necessarily your value: existing holders’ stake falls when new shares are issued, but the company may be worth more afterwards.
- The basic formula: post-money = pre-money + investment; investor ownership = investment ÷ post-money.
- Always model on a fully diluted basis, and always model the option pool and the round together, because a pre-money pool lands on founders.
- Treat every SAFE or convertible note as its own line, tested under downside, base and upside valuations.
- In the UK, finish with a legal checklist: authority to allot, class rights, pre-emption and the Companies House filing.
Table of Contents
- What an equity dilution model actually does
- The core maths in four lines
- A worked example: seed round, option pool, then Series A
- Option pool dilution: model the timing, not just the percentage
- SAFEs and convertible notes are dilution too
- A UK workflow for building the model
- Go beyond a single-round calculator
- Common mistakes in dilution models
- Perspective: what we see founders get wrong
- When to bring in a fractional CFO
- FAQ
- Sources
What an equity dilution model actually does
A dilution model is a cap table that looks forwards. A static cap table tells you who owns what today. A model tells you who will own what after a seed round, a Series A and a sale, and what that ownership is worth in cash at each stage.
A useful output has seven parts:
- a pre-round and post-round cap table
- ownership by holder
- the dilution percentage
- the new share price
- the remaining option pool
- a conversion schedule for any SAFEs or notes
- an exit waterfall
If your model only produces one number, the investor’s percentage, it will miss the things that actually move your outcome. For the tracking side of this, see our guide to cap table management. For the concept itself, we have a separate practical guide to equity dilution for UK founders.
The core maths in four lines
The standard round arithmetic, as set out in Gust’s round model guide, is:
- Post-money valuation = pre-money valuation + new investment.
- Investor ownership = investment ÷ post-money valuation.
- Price per share = pre-money valuation ÷ pre-round fully diluted shares.
- Each existing holder’s new ownership = their unchanged shares ÷ fully diluted post-round shares.
Take a £2 million pre-money valuation and a £500,000 investment. Post-money is £2.5 million and the investor owns 20%. Everyone else holds 80% between them, so a holder who had 100% now has 80%. That is 20% dilution in percentage terms.
“Fully diluted” matters in line 3 and line 4. Include issued shares, granted options, the unallocated pool, warrants and anything expected to convert. Leaving out reserved options is the most common way a first model flatters the founders.
A worked example: seed round, option pool, then Series A
Let us follow two founders who together hold 1,000,000 ordinary shares, 100% of the company. The investor asks for a 10% option pool, measured on the post-round share count and created before the investment is priced.
Step 1: the round without a pool
Without a pool, the £500,000 buys 20% of a company valued at £2.5 million post-money. The company issues 250,000 new shares at £2.00 each. Total shares: 1,250,000. Founders hold 80%.
Step 2: add the pool in the pre-money
Now the pool arrives. The investor needs 20% and the pool needs 10% of the post-round total, so the founders’ 1,000,000 shares must represent the remaining 70%.
| Holder | Shares | Ownership |
|---|---|---|
| Founders | 1,000,000 | 70.0% |
| Option pool | 142,857 | 10.0% |
| Seed investor | 285,714 | 20.0% |
| Total | 1,428,571 | 100% |
The price per share is £500,000 ÷ 285,714, which is £1.75. The headline pre-money was £2 million, but the founders’ own shares are valued at 1,000,000 × £1.75 = £1.75 million. The pool has quietly reduced the effective pre-money valuation by £250,000. Founders end at 70% rather than 80%, and the investor’s 20% is untouched.
This is why a pool request is often the negotiation hidden inside the headline valuation. AngelList’s option pool explainer makes the point that the same target percentage produces very different founder outcomes depending on whether it sits before or after the money goes in.
Step 3: the next round
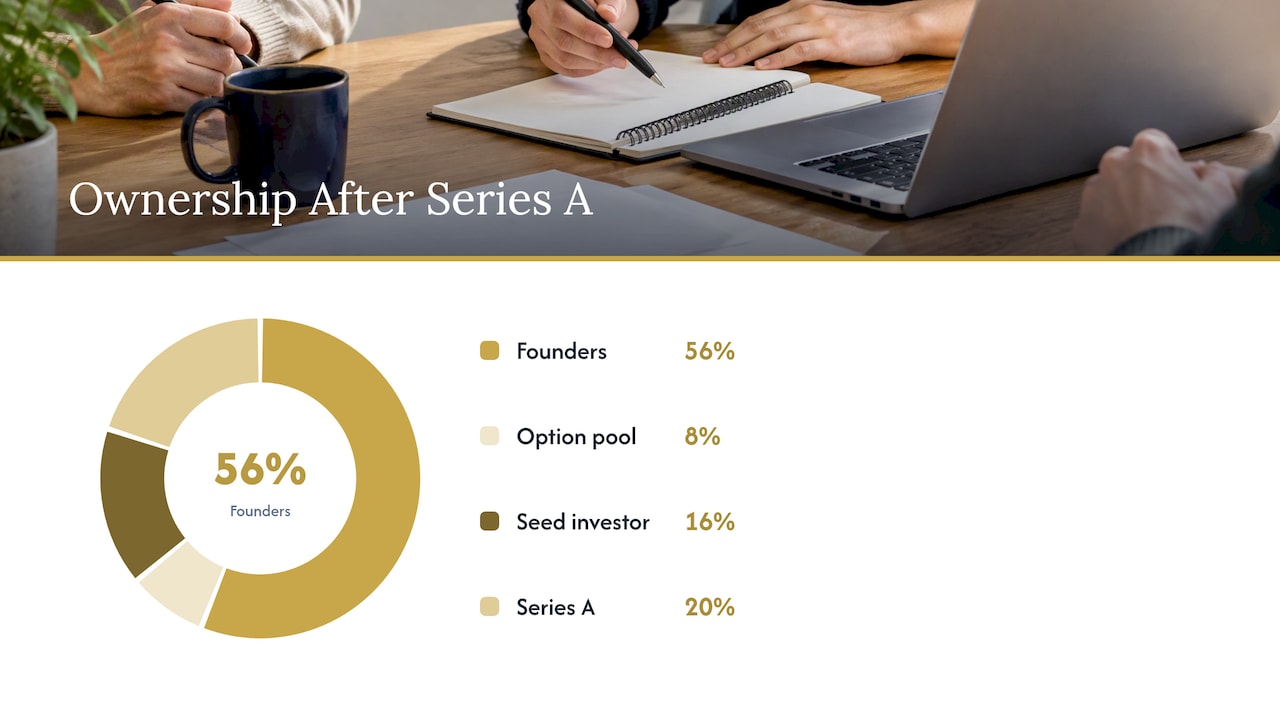
Suppose a Series A of £3 million is raised at £12 million pre-money. Post-money is £15 million, so the new investor takes 20%. Everyone existing is diluted by one fifth.
| Holder | Seed stage | After Series A |
|---|---|---|
| Founders | 70.0% | 56.0% |
| Option pool | 10.0% | 8.0% |
| Seed investor | 20.0% | 16.0% |
| Series A investor | n/a | 20.0% |
If the company also tops up the pool in this round, the founders fall further. Say the pool is topped up to 10% post-round, in the pre-money again: founders end nearer 54%. That top-up is the number a first-round model tends to leave out.
In this example the founders’ stake at round prices is the same before and after (70% of £12 million is £8.4 million, and 56% of £15 million is £8.4 million). The point to report is both figures: the percentage fell, and the implied value did not. Value rises only if the next valuation is higher than the price you would otherwise have reached.
The figures are illustrative. They are not a forecast of what any real round will look like.
Option pool dilution: model the timing, not just the percentage
The research is consistent on one point: the denominator matters. A pre-money top-up is included in the share count before the investor’s shares are priced, so founders and existing holders absorb it. A post-money pool is added after the financing and dilutes the new investor too. A term sheet that says “10% pool” without saying when it is measured has not told you very much.
Build these into the model as explicit inputs:
- the pool target as a percentage
- whether it is measured pre-money or post-money
- whether it is measured on the post-round or the pre-round share count
- how much of the pool is already granted, so you are topping up rather than starting fresh
Also separate the stages of an option: reserved, granted, vested and exercised. Vesting does not remove an option from a fully diluted calculation, so unvested options still count.
A sensible check is to size the pool from your hiring plan. List the senior roles you expect to hire in the next 18 to 24 months, attach a realistic grant to each, and total the result. If that is well below what the investor requests, you have an evidence-based argument for a smaller pool. Our guide to VC term sheet red flags covers other clauses worth reading at the same time.
SAFEs and convertible notes are dilution too
A SAFE is not “not yet diluted”. It converts at the next priced round and takes a share of the company when it does. Its cap, discount, whether it is pre-money or post-money, any pro-rata side letter and its conversion trigger all change the next cap table.
For the model:
- Enter each instrument on its own row with principal, cap, discount, MFN status and pro-rata rights. Do not blend them into one generic percentage.
- Calculate conversion at the lower of the cap price and the discounted round price, where the agreement uses that mechanism.
- For a convertible note, add accrued interest and check the maturity date. A SAFE in its standard form has no interest or maturity.
Post-money SAFEs are simpler to forecast. DLA Piper’s SAFE FAQs explain that the cap is based on ownership after all SAFE money is counted, but before the new money in the priced round. So a £250,000 post-money SAFE at a £5 million cap is intended to convert into 5% of the company at that point, before the new round and before any pool top-up.
The catch is that more than one SAFE, or a priced round close to the cap, can produce a different result from the estimate. The Y Combinator quick start guide warns that the SAFEs may convert into more than the estimated ownership in that situation. Run the model at a downside, base and upside round valuation before you sign anything.
A UK workflow for building the model
The order below keeps the spreadsheet and the legal paperwork in step.
- Establish the current cap table. List every shareholder, share class and number of shares, and reconcile to your statutory registers.
- Confirm share classes and rights. Under the Companies Acts, a share carries voting, dividend and capital rights, and the particulars of those rights are filed. Your model should reflect them, not treat every share as identical.
- Convert everything to a fully diluted basis. Include granted options, the unallocated pool, warrants and expected conversions.
- Enter pre-money valuation and investment. Use the term sheet figures, not the ones from the first conversation.
- Model pool timing. Pre-money or post-money, as above.
- Calculate new shares, price per share and post-round ownership.
- Stress-test future rounds and exit proceeds.
- Reconcile to the legal documents and Companies House filings.
The legal checklist beside the numbers
Issuing shares in a UK company is not only arithmetic. Before the new shares exist, check that the directors have authority to allot, that the articles and any shareholders’ agreement do not give existing holders pre-emption rights you have overlooked, and that class rights are respected. UK government guidance on dilution is a helpful reference for the concept, and your solicitor will confirm the corporate steps.
Afterwards, the allotment is reported to Companies House on form SH01. The return must be filed within one month of allotment, and it records the number of shares, nominal value, amounts paid or unpaid and an updated statement of capital. If the share numbers in your model do not match what the SH01 will say, fix the model first. A mismatch tends to surface during due diligence, which is a bad moment to find it.
Go beyond a single-round calculator
A single-round calculator answers one question. If you are planning a funding path over the next one to three years, or heading towards a sale, you need more.
A model that supports real decisions will:
- compare staged rounds with one larger raise
- compare equity-heavy funding with a debt-heavy mix
- connect ownership to liquidation preferences, since a 1x non-participating preference and a participating one pay out very differently at the same exit price
- show MOIC and IRR for the investor and cash proceeds for each holder
- run anti-dilution terms where they exist
The Hemrock cap table tool and this cap table model example both show what a fuller structure looks like: ordinary and preferred shares, options, vesting, convertibles, several rounds and an exit waterfall. You can use a template like that as a learning aid, but check every formula against your own documents.
One warning for UK founders. A model built on a headline valuation can be misleading if you plan to sell. Fundraising valuation and exit valuation are not the same number, and the share of proceeds you receive depends on the structure you agreed at each earlier round. If you are earlier on the journey, our overview of the stages of funding shows how typical rounds stack up.
Common mistakes in dilution models
- Using issued shares instead of fully diluted shares. This overstates your ownership and misprices the round.
- Forgetting the pool top-up in later rounds. Each new investor may ask for a refreshed pool.
- Treating a SAFE as a future problem. It is a future cap table line, and it should be in the model today.
- Reporting only percentages. Show implied value too, so a board can see that a smaller slice of a higher-valued company can be worth more.
- Hard-coding numbers. Link inputs to a single assumptions sheet, so changing the valuation or pool size updates everything.
- Ignoring the paperwork. A beautiful model that does not match the articles, the investment agreement and the SH01 is a due diligence problem. Our investor due diligence checklist and guide to responding to investor questions show what investors ask to see.
The Investment Association’s guidance on share capital management is written for listed companies, but the discipline it describes applies to private boards as well: explain capital raising in terms of structure and shareholder protections, not just the number of shares issued.
Perspective: what we see founders get wrong
We are ICAEW Chartered Accountants working as fractional CFOs with SaaS companies and ambitious UK SMEs, and the pattern is consistent. Founders focus on the valuation number and the cash raised. The investor’s lawyers focus on the pool, the instruments and the preferences.
Our view is that the model should be built before the term sheet arrives, not after. When a founder walks into a negotiation with a cap-table range already prepared, showing downside, base and upside outcomes, the conversation shifts from “do we like this headline” to “which of these terms costs us most”. That is a far stronger position.
We also think dilution should be judged against what the money achieves. Ten per cent given up to reach a metric that lifts the next valuation by far more than ten per cent is a good trade. Ten per cent given up to extend runway by two months is not. A model that links funding to your MRR, churn and hiring plan makes that comparison visible.
— Kishen Patel
When to bring in a fractional CFO
A spreadsheet you built yourself is fine for a first look. It stops being enough when you have several instruments, a pool negotiation, or an investor who will test every formula. That is where our investor-grade financial modelling service helps: a model that ties ownership to your forecast, your funding options and your exit. If you want ongoing senior finance support through a raise, our fractional CFO services give you ICAEW Chartered Accountant-led guidance without a full-time hire.
FAQ
What does dilution mean for shareholders?
It means their percentage ownership falls when the company issues new shares, whether for funding, employee options or convertible securities. Their voting, dividend and exit percentages all need recalculating. The value of their holding does not have to fall, because the company may be worth more after the new money arrives.
Is a pre-money or post-money option pool better for founders?
A post-money pool is usually kinder to founders, because it dilutes the new investor as well. A pre-money pool is more common in term sheets and lands on existing holders. Whichever is offered, negotiate the timing and the measurement basis as well as the percentage.
How much dilution is normal in a funding round?
It varies by stage, valuation and structure, so any single figure is a rough guide only. A UK cap table planner suggests a priced seed round plus a fresh pool can cost founders roughly 25% to 30% combined. Build your own scenarios rather than relying on an average.
Do SAFEs dilute founders before they convert?
Not in the issued share count, but they must be in your fully diluted model from the day you sign. When they convert, they take shares based on the cap or discount. Model each one separately so you can see the effect on the next priced round.
Do I need to tell Companies House about new shares?
Yes. An allotment of shares is reported on form SH01 within one month, with an updated statement of capital. Your solicitor or company secretary will usually prepare it, but check that the numbers match your model.
Sources
- Knowledge Asset Spinouts Guide (UK government)
- Gust: round model math
- AngelList: what is an employee option pool
- FFI Standard: capital structure
- DLA Piper: SAFE FAQs
- Y Combinator SAFE quick start guide
- The Companies (Shares and Share Capital) Order 2009
- Form SH01 filing guidance
- Hemrock cap table tool
- Cap table model example
- Investment Association: Share Capital Management Guidelines 2023
- Free cap table planner for UK startups
Recommended
- Equity dilution explained: a practical guide for UK founders
- Become Investor Ready: A Practical Guide for UK Founders
- Scenario Planning for UK Startups Raising Their Next Round
- Cap Table Management: The Founder’s Investor-Ready Guide
This article is for general information only and is not professional advice.
Not sure where your business stands right now?
Book a free 30-minute call with Kish. Bring your numbers, your questions, or just your situation. You will leave with a clearer picture than you arrived with.
Book a Free Strategy Call
Over 12 years across Big Four audit, Investment Banking, and corporate advisory. Kish works with SaaS founders, tech companies, and ambitious UK SMEs from £1M to £50M in revenue on fundraising, valuations, exit planning, and financial strategy. ICAEW regulated. Big Four trained. Based in London.