

There are four working capital levers: collect from customers faster, hold less stock, use supplier terms deliberately, and, when those fall short, fund the gap with the right finance. Pulling the right lever depends on where your cash is stuck, and you can only see that with a forecast built on debtor days, stock days and supplier days. For founders raising a round, SaaS teams stabilising cash, and owners preparing for a sale, these numbers also shape how investors and buyers read your business. A fractional CFO can take that analysis off your hands: our Fractional CFO services give you senior finance leadership without a full-time salary.
TL;DR
- Working capital is the money that funds day-to-day operations, and it is often tied up with customers, suppliers and HMRC, or in stock and work in progress.
- The main levers are receivables (debtor days), inventory (stock days), payables (supplier days) and short-term financing.
- Start by measuring debtor days, inventory days and supplier days in a cash flow forecast, then act on the largest pool of trapped cash first.
- Track the current ratio and quick ratio, and keep both above 1:1, so the gains hold.
- If you plan to sell, working capital is also a negotiated number in the deal, so improving it early protects your price.
Table of Contents
- What improving working capital actually means
- Step one: find where the cash is stuck
- Lever 1: receivables, getting paid sooner
- Lever 2: inventory, holding less without losing sales
- Lever 3: payables, using supplier terms with care
- Lever 4: operations and structure
- Lever 5: financing the gap
- Which lever first?
- Make the gains stick
- Why working capital matters when you raise or sell
- Where a fractional CFO helps
- Getting senior help on your cash cycle
- FAQ
- Sources
What improving working capital actually means
The British Business Bank describes working capital as the money available to fund day-to-day operations. It is often tied up with customers, suppliers and HMRC, or used for stock and work in progress. It adds that managing it more effectively can make a business more resilient and reduce its need for growth finance.
In practice, improving working capital means shortening the time between paying for something (wages, stock, hosting, contractors) and being paid for what you sell. Cash that would otherwise sit in a customer’s bank account or on a warehouse shelf stays in your business instead.
The basic calculation is simple:
Net working capital = current assets (cash, debtors, stock) minus current liabilities (creditors, short-term debts, tax due)
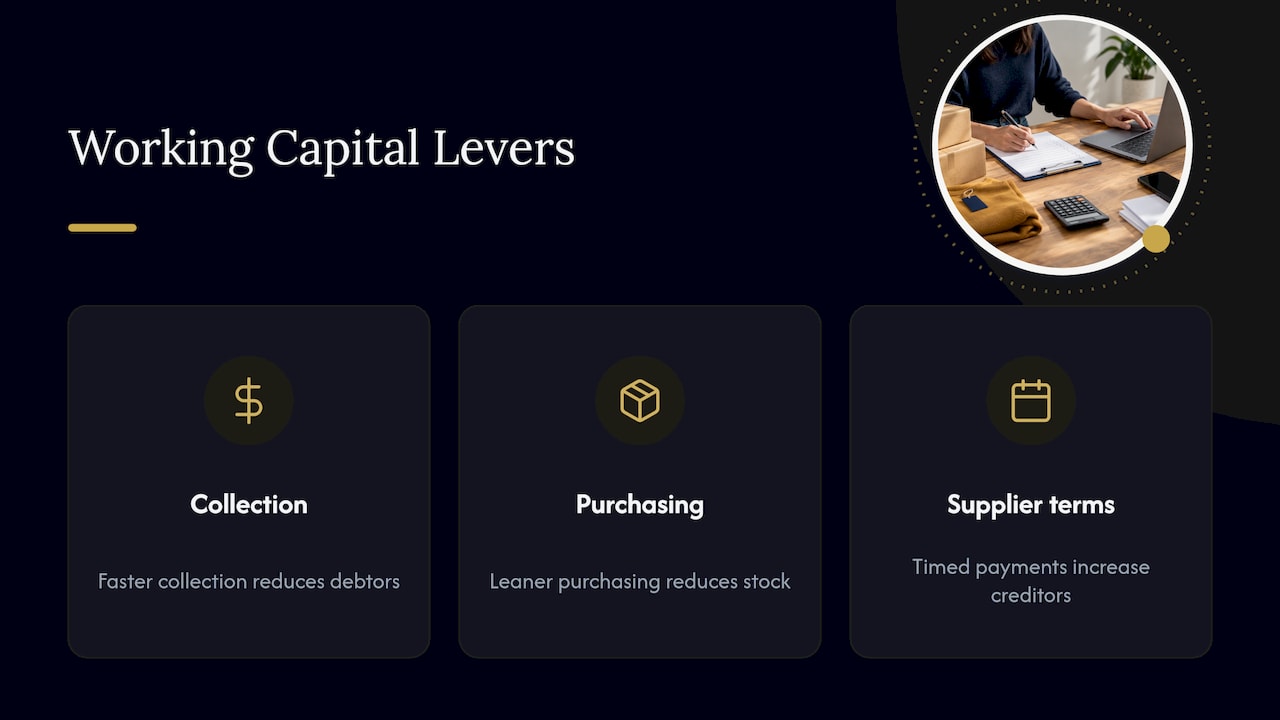
The levers act on the components. Faster collection reduces debtors. Leaner purchasing reduces stock. Better-timed supplier payments increase creditors, which funds the business for longer. None of these changes your profit on paper, which is why a profitable company can still run short of cash. If that sounds familiar, our page on profitable businesses running out of cash covers the pattern in more detail.
Step one: find where the cash is stuck
Before choosing a lever, measure. ICAEW advises including cash in hand, debtor days, inventory days, supplier days taken and total sales in your cash flow forecast. With those in front of you, management can see where cash is trapped and decide what to do.
The three day-counts are:
- Debtor days: the average time customers take to pay you. Trade debtors divided by annual sales, multiplied by 365.
- Inventory days: how long stock sits before it is sold. Stock divided by annual cost of sales, multiplied by 365.
- Supplier days: how long you take to pay suppliers. Trade creditors divided by annual cost of sales, multiplied by 365.
The gap between the first two and the third is your cash cycle. The longer it is, the more cash your business must fund from its own pocket or from borrowing.
A worked example
Take an illustrative UK services and product business with £3.65m annual sales and £2.19m cost of sales. It has £600,000 of trade debtors, £360,000 of stock and £240,000 of trade creditors.
| Measure | Calculation | Result |
|---|---|---|
| Debtor days | £600,000 / £3,650,000 x 365 | 60 days |
| Inventory days | £360,000 / £2,190,000 x 365 | 60 days |
| Supplier days | £240,000 / £2,190,000 x 365 | 40 days |
| Cash cycle | 60 + 60 – 40 | 80 days |
Each day of debtor days is worth £10,000 of cash here (£3.65m divided by 365). Cutting debtor days from 60 to 50 releases £100,000 without a single extra sale. Each day of stock or supplier days is worth £6,000 (£2.19m divided by 365). The example is invented to show the arithmetic, but your own figures will produce the same kind of league table: the lever with the most days and the most value per day comes first.
Lever 1: receivables, getting paid sooner
For most B2B companies, this is the biggest and fastest lever, because it depends on your own processes rather than on anyone else’s goodwill.
ICAEW lists simple working capital measures that include an improved process for chasing debtors and agreeing payment terms in advance. Here is how that turns into a routine:
- Agree terms before work starts. Put payment terms in the contract or order, and for project work consider staged invoices rather than one bill at the end.
- Invoice promptly and accurately. Many late payments start with an invoice that is late, missing a purchase order number or sent to the wrong person.
- Chase on a schedule. A polite reminder before the due date, one on the day and a call a few days after is a process, not an argument. Assign it to one named person.
- Review the ledger weekly. Look at the largest and oldest items first. A handful of customers usually account for most of the overdue value.
- Watch concentration. If one customer owes a large share of your debtors, their payment habits set your cash position.
For SaaS businesses, the equivalent is billing design. Annual upfront billing in place of monthly billing brings cash in earlier, and reducing failed card payments and involuntary churn protects the cash you have already won. Cleaner collection also supports steadier MRR and churn reporting, which is exactly what investors examine.
Lever 2: inventory, holding less without losing sales
If you carry stock or work in progress, inventory days can lock up more cash than debtors do. The British Business Bank, citing a working capital specialist, suggests that businesses review lead times, safety stock and cycle stock, engage suppliers early and evaluate warehousing needs ahead of key trading times.
Practical moves:
- Segment your stock. Split products into fast, medium and slow movers. Slow movers tie up cash for the least return, so reduce reorder quantities first.
- Set safety stock deliberately. Base it on lead time and demand variability rather than on a habit of ordering extra.
- Keep records accurate. You cannot cut stock confidently if your counts are unreliable. A routine such as cycle counting by ABC category keeps high-value items counted more often without stopping operations.
- Plan ahead of peaks. Talking to suppliers before a busy season avoids both emergency orders and over-ordering.
A simple test: if you reduced stock by five days in the example above, you would release £30,000. Compare that against any risk of lost sales before you commit.
Lever 3: payables, using supplier terms with care
Paying suppliers later keeps cash in your business for longer, and the British Business Bank recommends engaging suppliers and customers to share assumptions and to renegotiate contracts so they reflect changed commercial realities. The operative word is engaging: agreed terms, not unilateral delay.
What to weigh:
- Negotiate, do not stretch. Ask for longer terms in return for volume, reliable forecasts or a longer contract. A supplier who is told in advance is far more flexible than one who is paid late without warning.
- Check early-payment discounts. A discount for paying early can be worth more than the cash you keep by paying late. Compare the discount’s implied annual return with the cost of your borrowing before choosing.
- Protect critical suppliers. Paying key suppliers on time protects supply, pricing and your reputation.
- Know your legal position. Late payment between businesses is governed by UK late payment rules, so check the current rules on gov.uk and your contract terms before relying on extended payment periods.
Supplier days is the lever where a quick win can create a long-term problem, so treat it as a negotiated term rather than a habit.
Lever 4: operations and structure
Some of the cash is released by how the business is run, not by chasing individual balances. ICAEW’s list includes the option of renting rather than buying equipment or vehicles, and taking collective responsibility for the cash position, for example moving from one month of available cash to two or three. Related habits include:
- Avoid funding big asset purchases out of day-to-day operating profits.
- Review owner withdrawals against forecast cash, not just against profit.
- Avoid overtrading: growing sales faster than your cash can fund them. Fast-growing companies, including SaaS businesses with rising hosting and hiring costs ahead of revenue, are especially exposed.
- Make cash a shared target across sales, operations and finance, not only a finance topic.
Lever 5: financing the gap
When operational changes do not release enough cash, or growth needs more than the cycle can supply, financing is the final lever. ICAEW advises speaking to your bank well ahead of a potential shortfall, notes that debt factoring can reduce customer receipts but ease collection, and suggests selling and leasing back assets such as machinery.
The common point is timing: arrange funding before you need it, while your forecast still shows headroom. Lenders respond better to a business that presents a credible forecast than to one asking in a crisis. Asset-backed structures are one route, and our guide to asset based lending in the UK explains how they work. For what lenders look at, see debt finance for UK SMEs.
Which lever first?
| Your situation | Start with | Why |
|---|---|---|
| Long debtor days, few stock items (services, SaaS) | Receivables | Fastest release, within your control |
| Product business with slow-moving lines | Inventory | Large cash value per day |
| Healthy margins but seasonal peaks | Financing and supplier terms | Smooths timing rather than removing it |
| Growing fast, cash tight despite profit | Forecast first, then all levers | Overtrading needs a plan, not one fix |
Make the gains stick
A one-off clean-up fades unless you measure. ICAEW says a cash flow dashboard should track the current ratio and the quick ratio, and that both should be above 1:1 so that obligations can be paid. The current ratio is current assets divided by current liabilities. The quick ratio is the same, with stock removed from the assets.
ICAEW also stresses that a forecast should be flexible but, above all, practical, indicating whether you need to borrow, how much, and when and how you will repay. Review it regularly and compare actual cash against it in detail. A rolling 13-week cash flow forecast is the usual short-term tool, and cash flow scenario analysis shows what a late-paying customer or a lost contract would do to your headroom. Our cash runway stress test page covers the same ground for businesses watching their runway.
Why working capital matters when you raise or sell
Investors and buyers read your working capital as evidence of how well the business is run. Lumpy collections and unexplained swings in stock raise questions in due diligence, and a messy cash cycle makes forecasts harder to trust.
In a sale, the buyer usually expects a normal level of working capital to be left in the business, and the price is adjusted if the closing figure is above or below an agreed target, often called a peg. If you plan to sell in the next one to three years, the months you spend tightening collections and stock are the months that make that target easier to defend. Our working capital guide sets out how the peg works, and our guide to exit planning shows where it fits among other preparation.
Where a fractional CFO helps
Working capital sits between sales, operations and finance, and no one in a growing business owns it by default. Our page on profitability and working capital improvement sets out how we approach it.
Our view
Most founders treat working capital as a bookkeeping outcome. We treat it as a decision. Every day of debtor days, stock or supplier terms is a choice about who funds your growth, you, your customers, your suppliers or a lender.
The businesses we see handled best start with a forecast they trust, then pull levers in order of value. That is the discipline of a senior finance leader, and it is what we bring through fractional engagements: investor-ready metrics and the rigour of a Big Four-standard approach, without a full-time CFO’s cost.
If you are raising, scaling or preparing to sell, the cash cycle is part of the story you tell. We would rather help you shape it early than explain it later in due diligence.
Kishen Patel
Getting senior help on your cash cycle
Consult EFC is led by ICAEW Chartered Accountant Kishen Patel. We provide fractional CFO services, financial planning and analysis, and investor-grade modelling for high-growth companies and ambitious UK SMEs. If you want a working capital review tied to your forecast, funding plans or exit timetable, start with our fractional CFO services, or see our FP&A services for regular reporting and analysis.
If a funding round or sale is on the horizon, our investor-grade financial modelling turns your working capital assumptions into numbers investors can test.
FAQ
What does it mean to improve working capital?
It means releasing cash that is tied up in the day-to-day cycle of customers, stock and suppliers, so the business needs less outside funding to operate. You do this by collecting faster, holding less stock and agreeing sensible supplier terms. The result is a stronger, more resilient cash position.
How do I calculate the working capital gap?
Start with current assets (cash, debtors, stock) and subtract current liabilities (creditors and short-term debts). To see the drivers, calculate debtor days, inventory days and supplier days, then forecast them forward. The cash cycle is debtor days plus inventory days minus supplier days.
How can I increase cash flow quickly?
The fastest lever is usually receivables: invoice promptly, agree terms upfront and chase on a fixed schedule. Review your largest overdue balances first. Then check whether short-term finance is needed, and arrange it before a shortfall appears.
Which ratios show that working capital has improved?
Track debtor days, inventory days and supplier days, alongside the current and quick ratios. ICAEW says both ratios should be above 1:1. Reviewing them monthly against a forecast shows whether the change is lasting.
Sources
- Dealing with working capital problems, British Business Bank
- Financial management, ICAEW
- Cycle counting inventory: ABC method and schedule
Recommended
- Profitability and Working Capital Improvement UK
- Profitable but Running Out of Cash?
- Cash Runway Stress Test
- Growth Finance Reset: 90-Day Cash Flow, Pricing, Cost Cuts
This article is for general information only and is not professional advice.
Not sure where your business stands right now?
Book a free 30-minute call with Kish. Bring your numbers, your questions, or just your situation. You will leave with a clearer picture than you arrived with.
Book a Free Strategy Call
Over 12 years across Big Four audit, Investment Banking, and corporate advisory. Kish works with SaaS founders, tech companies, and ambitious UK SMEs from £1M to £50M in revenue on fundraising, valuations, exit planning, and financial strategy. ICAEW regulated. Big Four trained. Based in London.