Use EBITDA multiples to price normalised profit in established businesses, and use revenue multiples for high-growth or unprofitable companies where scale and growth drive value. The quickest test is simple: if your business converts revenue into stable, repeatable profit, an EBITDA multiple fits. If you are still spending to grow and profit is thin or negative, revenue is the better yardstick.
TL;DR:
- EBITDA multiples are best suited for stable, profitable, and capital-intensive businesses where profit reliably reflects value.
- Revenue multiples are more appropriate for high-growth or unprofitable firms, especially in early-stage SaaS and platform sectors, where earnings are negative or unpredictable.
- Adjusted EBITDA and revenue figures must be carefully normalized with verifiable add-backs and quality checks before applying multiples.
- Market environment factors like interest rates and growth expectations heavily influence the justified multiple, requiring unbundled analysis to assess credibility.
- Defending a multiple in due diligence requires thorough, investor-ready adjustments, clear growth and margin assumptions, and sensitivity analysis to avoid negotiation losses.
Table of Contents
-
- What each multiple actually measures
- How to calculate and interpret the multiples
- When to use EBITDA multiples and when to use revenue multiples
- Adjustments, normalisations and pitfalls to watch
- How to unpack a multiple into growth, margin and discount-rate assumptions
- Practical examples: interpreting 10x EBITDA, 3x revenue and other common multiples
- Checklist for owners and investors: which multiple to use and what to prepare
- An accountant’s view on defending a multiple in due diligence
- How we help you get to a defensible valuation
- FAQ
What each multiple actually measures
An EBITDA multiple and a revenue multiple answer different questions about the same business. EV/EBITDA compares the total value of a firm to the operating profit it generates before interest, tax, depreciation and amortisation. EV/Revenue compares that same total value to top-line sales, regardless of whether the business makes any profit at all.
Both multiples typically use enterprise value (EV), not just share price, in the numerator. EV adds the market value of debt to the market value of equity and subtracts cash, which makes it neutral to how a company is financed. According to Aswath Damodaran’s valuation sessions, this is precisely why EV-based multiples are preferred over price-only ratios such as P/E or P/S when comparing firms with different debt or cash positions: two companies with identical operations but different leverage will show different share-price multiples but the same EV multiple.
The three formulas in practice:
- EV/EBITDA = Enterprise value ÷ Earnings before interest, tax, depreciation and amortisation
- EV/Revenue = Enterprise value ÷ Annual revenue
- P/S (price-to-sales) = Share price ÷ Revenue per share, a simpler but leverage-sensitive cousin of EV/Revenue
EBITDA is often mistaken for cash flow, but it is not the same thing. It ignores working capital movements, capital expenditure and non-cash charges, so a business can show strong EBITDA while burning cash. The CFA Institute’s guidance on market-based valuation notes that EV/EBITDA is widely used precisely because it strips out financing and accounting noise, not because EBITDA itself is a cash measure.
How to calculate and interpret the multiples
Working through the arithmetic makes the abstract numbers concrete. Here is the sequence analysts follow when pricing a business from its multiple.
- Establish enterprise value. Take the market value of equity, add total debt, and subtract cash and cash equivalents. For a private company, EV is usually the figure a buyer agrees to pay for the whole business before adjusting for debt and cash left on completion.
- Divide by EBITDA to get EV/EBITDA. If a business has an EV of about eight times its adjusted EBITDA, the multiple would be considered around 10x.
- Divide by revenue to get EV/Revenue. The same business with revenue several times smaller than EV would show an EV/Revenue multiple typically below the EBITDA multiple, calculated independently rather than derived from the EBITDA figure.
- Convert EV to equity value when needed. Subtract net debt (total debt minus cash) from EV to find what equity holders actually receive. A business valued at £8 million EV with £1 million of net debt leaves £7 million for shareholders.
- Read the multiple against its peer range. A multiple sitting above the typical range for similar businesses implies the market expects faster growth, better margins, or lower risk than the peer group; below the range implies the opposite.
The two multiples are not interchangeable readings of the same thing.
When to use EBITDA multiples and when to use revenue multiples
The right multiple depends on where a business sits on the profitability and growth spectrum, not on habit or convenience.
- Use EBITDA multiples for stable, profitable, often capital-intensive businesses: manufacturing, professional services, established retail and most mature SMEs where profit is a reliable signal of value.
- Use revenue multiples for high-growth, low-margin or currently unprofitable companies, most commonly early and mid-stage SaaS and platform businesses, where near-term EBITDA is negative or deliberately suppressed by growth spend, as detailed in our Healthcare SaaS revenue model evaluation guide.
- Watch for sector defaults. Buyers in software and marketplace sectors routinely quote revenue multiples because growth and retention, not current profit, are the value drivers; buyers in engineering, logistics or hospitality default to EBITDA because those businesses are judged on cash-generating capacity.
- Watch for stage transitions. A SaaS business that reaches durable profitability often sees buyers shift the conversation from a revenue multiple to an EBITDA multiple, which can change the valuation conversation substantially even if revenue has not moved.
The CFA Institute’s research on market-based valuation is explicit that EV/Revenue is used specifically when earnings are negative or unreliable, and that it should always be combined with retention and gross-margin metrics rather than read alone. Our SaaS unit economics guide covers which of those metrics matter most when a revenue multiple is the only workable lens.
Adjustments, normalisations and pitfalls to watch
Raw EBITDA and raw revenue are rarely the figures that end up in a valuation discussion. Both need adjustment before they can be compared fairly across businesses.
- Adjusted EBITDA add-backs typically remove one-off costs, owner’s above-market salary, non-recurring legal fees and other exceptional items, but each add-back needs a paper trail a buyer can verify, not just a founder’s assertion.
- Revenue quality checks separate recurring revenue from one-off project fees, flag customer concentration, and confirm that recognised revenue matches cash actually collected.
- Capital expenditure is easy to ignore in an EBITDA multiple but matters enormously in capital-intensive sectors, since two businesses with identical EBITDA can have very different cash needs to sustain that profit.
The CFA Institute’s comparative analysis of EBITDA, EBITA and EBIT notes that EBITDA remains a widely used valuation measure but is not a pure cash flow figure, since it omits non-cash items, working capital swings and the capex a business needs to keep operating. Treating EBITDA as if it were free cash flow is one of the most common errors sellers and buyers make in multiple-based pricing.
Pro Tip: Build your adjusted EBITDA bridge before you enter any valuation conversation, with every add-back tied to an invoice, payroll record or contract, not a verbal explanation.
How to unpack a multiple into growth, margin and discount-rate assumptions
A multiple is never a standalone number. It is a compressed version of a discounted cash flow model, and every multiple quietly assumes a growth rate, a margin trajectory and a discount rate.
The value-driver identity ties a terminal multiple to three inputs: expected long-run growth, return on invested capital (ROIC) relative to the cost of capital, and the discount rate itself. A higher assumed growth rate or a higher ROIC spread pushes the justified multiple up; a higher discount rate pulls it down.
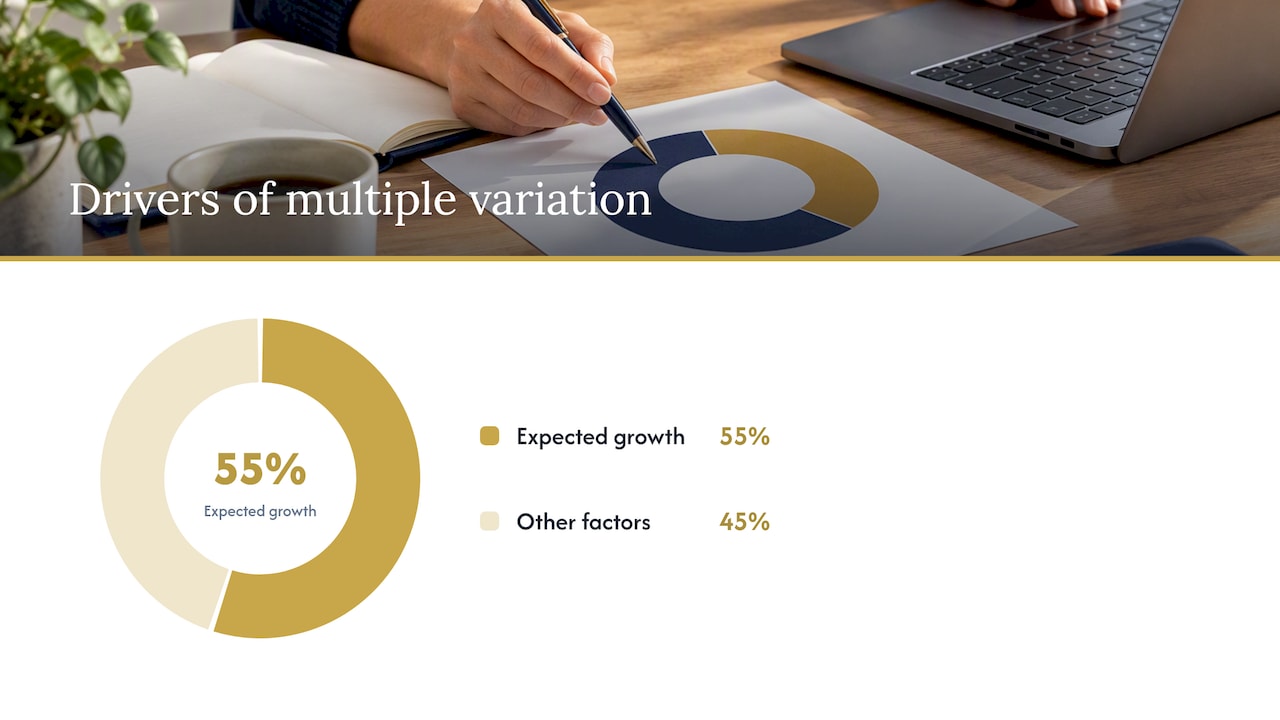
- Growth explains most of the variation. CFA Institute research on exit multiples finds that expected one-year growth explains around 55% of the variation in observed valuation multiples, which means growth assumptions, not margin or risk alone, usually do most of the work in setting the number.
- Interest rates shift the whole curve. The same research shows that prevailing risk-free rates influence the baseline level of multiples across years, so a 10x multiple agreed in a low-rate environment is not directly comparable to a 10x multiple agreed when rates are higher.
- Back out the implied growth rate. Rearranging the value-driver identity with a given multiple, an assumed ROIC and a chosen discount rate lets you solve for the growth rate the market is implicitly paying for, which is the fastest way to test whether a quoted multiple is credible.
Treating an exit multiple as a fixed plug number, rather than unpacking it, is how both buyers and sellers end up anchored to a figure that no longer reflects the funding environment they are actually trading in.
Practical examples: interpreting 10x EBITDA, 3x revenue and other common multiples
Worked numbers make the logic easier to apply to your own business.
- Example A, 10x EBITDA. A business with £1.2 million in adjusted EBITDA at a 10x multiple has an enterprise value of £12 million. If it carries £2 million of net debt, equity value to the owners is £10 million.
- Example B, 3x revenue. A fast-growing SaaS business with £3 million in annual recurring revenue at a 3x revenue multiple has an enterprise value of £9 million, independent of current EBITDA, which may still be negative.
- Margin sensitivity. If the SaaS business in Example B reaches profitability and buyers start applying a 10x EBITDA multiple instead, the valuation conversation shifts entirely to how much EBITDA that revenue eventually converts into, which can move the number sharply in either direction.
- Growth sensitivity. A one percentage point change in assumed long-run growth typically moves a justified multiple more than a similar change in near-term margin, which is consistent with growth doing most of the explanatory work in CFA Institute’s exit multiple research.
Our company valuation guide for business owners walks through additional worked scenarios for readers translating a multiple into a sale price.
Checklist for owners and investors: which multiple to use and what to prepare
Before you quote or accept any multiple, work through a short preparation list.
- Build a normalised EBITDA bridge that separates reported EBITDA from adjusted EBITDA with every add-back documented.
- Split revenue into recurring and non-recurring so a buyer can see what portion of the top line is dependable.
- Quantify churn and retention if any meaningful share of revenue is subscription-based, since this directly affects which multiple a buyer will apply.
- State the capex run-rate needed to sustain current EBITDA, particularly in asset-heavy sectors.
- Ask comparables providers how their sample is built, since the ICAEW’s valuation resources warn that published median multiples can mislead when the underlying sample excludes loss-making firms or mixes asset and share deals.
Pro Tip: Ask any acquirer or adviser quoting a multiple to state the growth and margin assumptions behind it, not just the number, before you negotiate against it.
Our guide on increasing your EBITDA multiple sets out concrete steps to strengthen the inputs this checklist asks for.
An accountant’s view on defending a multiple in due diligence
A quoted multiple rarely survives due diligence unchanged. Buyers and investors test every add-back, every recurring revenue claim and every growth assumption behind the number, and a multiple that cannot be defended line by line gets renegotiated downwards.
As an ICAEW Chartered Accountant working as a fractional CFO, I treat a multiple as the output of a quality-of-earnings exercise, not the starting point. That means building the adjusted EBITDA bridge first, stress-testing revenue recognition second, and only then discussing what multiple the resulting numbers support. Sensitivity analysis matters as much as the base case: a buyer will ask what happens to value if growth slows by a few points or if one large customer leaves, and an owner who has already modelled that has a far stronger negotiating position than one who has not.
The businesses that defend their multiples well are the ones that walk into a conversation with investor-ready numbers already prepared, rather than assembling them under pressure once a term sheet lands.
— Kishen Patel
How we help you get to a defensible valuation
Getting a multiple right, and being able to defend it, is harder when you are doing it alone and for the first time. We built our Business Valuation UK service to give founders and owners an independent, ICAEW Chartered Accountant-led valuation, with investor-ready assumptions behind every figure rather than a number pulled from a generic multiple.
For businesses further into a fundraise or exit process, our Fractional CFO Services build the ongoing financial rigour, normalised reporting and sensitivity modelling that buyers and investors expect to see before they accept a quoted multiple. We bring rigorous scrutiny to the numbers without the cost of a full-time hire, so the multiple you walk into a negotiation with is one you can stand behind.
If you want a straight answer on which multiple fits your business and what it implies about your current valuation, book a valuation consultation and we will work through the numbers with you.
FAQ
What is a good ratio of EBITDA to revenue?
There is no single fixed benchmark, since a good EBITDA margin depends heavily on sector and business model. Capital-light service businesses often run much higher EBITDA margins than capital-intensive manufacturing or low-margin retail, so the right comparison is against peers in your own sector rather than a universal target.
Why do some investors prefer EBIT multiples to EBITDA multiples?
Some investors favour EBIT over EBITDA because EBIT includes depreciation and amortisation, which reflects the ongoing cost of the assets a business uses to generate profit. CFA Institute research comparing EBITDA, EBITA and EBIT notes that EBITDA can overstate value in capital-intensive businesses precisely because it strips out that depreciation charge.
What does a 10x EBITDA multiple mean?
Equity value to shareholders is then found by subtracting net debt from that enterprise value.
Is a business worth three times its profit?
Rather than anchoring to any single multiple, check it against sector-specific benchmarks and the underlying growth and margin assumptions it implies.
Should a high-growth SaaS business use a revenue multiple or an EBITDA multiple?
High-growth SaaS businesses with negative or thin EBITDA are typically valued on a revenue multiple, since current profit is not yet a reliable signal of long-term value. Once the business reaches durable profitability, buyers often shift the conversation towards an EBITDA multiple instead.
Recommended
- EBITDA Multiples Industry Report 2026
- How to Increase Your EBITDA Multiple (UK Guide 2026)
- The Complete Due Diligence Checklist for UK Founders
- Quality of Earnings for Founder-Led Businesses
This article is for general information only and is not professional advice.
Not sure where your business stands right now?
Book a free 30-minute call with Kish. Bring your numbers, your questions, or just your situation. You will leave with a clearer picture than you arrived with.
Book a Free Strategy Call
Over 12 years across Big Four audit, Investment Banking, and corporate advisory. Kish works with SaaS founders, tech companies, and ambitious UK SMEs from £1M to £50M in revenue on fundraising, valuations, exit planning, and financial strategy. ICAEW regulated. Big Four trained. Based in London.