

Financial due diligence · UK businesses
Financial due diligence for business buyers and sellers.
Buying a business or preparing for sale? Get a clear view of earnings, cash and financial risks before the next deal decision.
Consult EFC helps you understand financial performance, cash needs and transaction risks. We agree the questions, investigate the available records and explain what the findings mean for your next commitment.
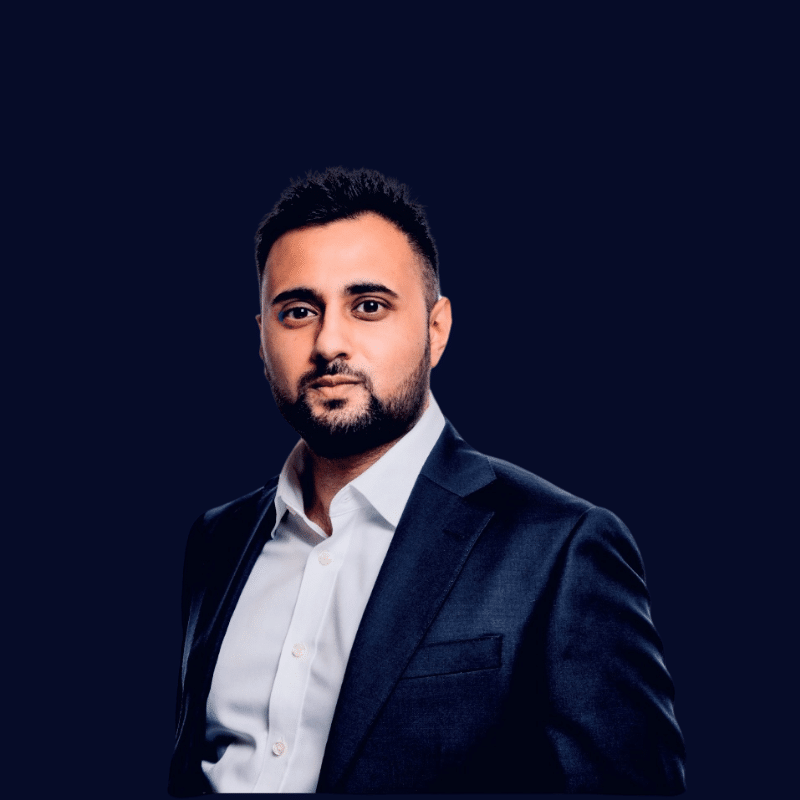
Kishen Patel ACA
ICAEW Chartered Accountant
Big Four audit and investment banking background
Start with the decision
Start with your side of the table
Financial due diligence is a defined investigation of a business’s financial information for a transaction or funding decision. Its value lies in the questions it answers, the evidence behind the findings and the limitations made clear to the intended readers.
Buying a business
Test the investment case before the next commitment.
- Sustainability of earnings
- Working capital and cash needs
- Net debt and price adjustments
Preparing to sell
Build an evidence trail before the buyer starts asking.
- Reconciled financial information
- Supported earnings adjustments
- A controlled response process
Funding or investing
Define the evidence required for the proposed funding decision.
- Historical performance and cash
- Forecast assumptions and downside
- Agreed recipients and reliance
Scope shaped around your situation
A review built around the questions that matter
Quality of earnings
Understand what sits behind reported profit. Review recurring performance, accounting judgements and proposed adjustments with supporting evidence.
Revenue and margin
Examine the mix of customers, products and contracts. Assess concentration, timing, retention and the cost of delivering revenue where relevant.
Working capital
Explore how much operating funding the business needs. Test seasonality, debtor quality, stock and the proposed transaction definition.
Cash and financing
Trace the relationship between profit and cash. Review borrowing, commitments and items that may need separate treatment in the price bridge.
Forecast resilience
Challenge the drivers behind the plan and model relevant downside cases. Distinguish management assumptions from evidence already observed.
Decision support
Present the implications, unanswered questions and options for further work. Financial findings inform the commercial discussion alongside legal and specialist advice.
For the decision in front of you
Choose the support that fits your transaction
I am buying a business
Challenge the target’s numbers, understand cash needs and identify findings that could affect your offer, funding or completion terms. Discuss a buyer financial review ↗
I am preparing to sell
Reconcile the financial story, support earnings adjustments and prepare for buyer questions before they become a distraction during negotiations. Discuss seller preparation ↗
I need the information organised
Build the financial schedules, document index and question tracker that make a review easier to manage. Plan a financial data room ↗
For owner-managed businesses, management buyouts, acquisition entrepreneurs and established acquirers. Our work is sector agnostic, including technology, AI, data, professional services and other UK SMEs.
Clear outputs. Defined responsibilities.
What you can expect to receive
The engagement letter sets the final deliverables, intended use, recipients and limitations. Your proposal should make those outputs easy to compare.
An agreed scope
The questions, information request, responsibilities, deadlines and reporting format.
Evidence-led findings
Analysis tied to the available records, with limitations and unresolved items highlighted.
A decision discussion
A walkthrough of the findings, their potential implications and the next actions within the agreed brief.
A practical working process
From the first question to the next decision
Define the decision
Tell us what you are considering, your role, the target business and the next deadline.
Agree the work
We establish scope, access, recipients, output, timetable and fee. Specialist workstreams are identified separately.
Investigate and discuss
We analyse the records, raise questions and surface important issues while the review is progressing.
Explain the implications
You receive the agreed output and a discussion of findings, limitations and priorities for the next stage.
Timing and fees are agreed after scoping. Data quality, access, the number of entities and the decision deadline all affect the work required. We raise material scope changes rather than assuming every extra request is included.
Agree the brief before work begins
Clear about the work. Clear about its limits.
Financial due diligence is not a statutory audit, a valuation opinion or a guarantee that every issue will be identified. Legal, tax, commercial, technology and operational reviews require their own scope. We identify the interfaces so the right advisers can address them.
For wider context, ICAEW explains the purpose and scope of financial due diligence. Your engagement should specify the actual work and intended use.
Your questions, answered
Financial Due Diligence Services UK: common questions
What does financial due diligence cover?
The agreed scope can include earnings quality, revenue, working capital, cash, net debt and forecasts. Coverage depends on the transaction, available records and intended use. The engagement letter should make inclusions and exclusions clear.
Is financial due diligence the same as an audit?
No. An audit and a transaction-focused financial review have different objectives, procedures and reporting. Financial due diligence should not be described as an audit opinion or blanket assurance over the business.
Can you work with buyers and sellers?
Yes, under separately agreed engagements. Buyer-side investigation and seller preparation serve different clients and purposes. We assess conflicts and responsibilities before accepting work.
Can a lender rely on the report?
Only where this is agreed. Tell us the lender or investor’s requirements before commissioning the work. Intended recipients, permitted use and reliance arrangements need to be confirmed in writing.
How long does the review take?
Timing depends on scope, information quality, access and responsiveness. We agree milestones around your decision dates. No fixed number of days is appropriate for every transaction.
How are the fees set?
The fee reflects the scope, entities, complexity, records, deadline and reporting requirements. We agree the fee and any change-control arrangements before starting.
Do you cover technology and AI businesses?
The financial scope can reflect recurring revenue, delivery costs, customer concentration, development expenditure and cash needs. Technical IP, cybersecurity and product validation require appropriate specialist work.
What should I send for an initial discussion?
Share your role, business or target sector, transaction stage, approximate size and deadline. Describe what financial information is available. Please do not send confidential records through the initial enquiry form.
Let’s define the next step
Tell us what you need to understand
Start with your situation and decision deadline. Please leave confidential documents out of the form; we can agree appropriate information sharing after the initial discussion.
We use your details to respond to your enquiry. Read our privacy policy.