For UK acquirers, management buyout teams and investors
Buy-side financial due diligence for UK acquisitions
Know what you are really buying before you sign.
Headline profit is only the starting point. Consult EFC tests the target's sustainable earnings, cash needs, net debt and financial risks, so you can decide whether to proceed, what to pay and what to protect in the deal.
Led personally by an ICAEW Chartered Accountant. London-based, working on acquisitions across the UK.
- ICAEW Chartered Accountant
- Big Four audit and investment banking background
- 12+ years' experience
- Defined scope, agreed fee
Clarity before commitment
What is buy-side financial due diligence?
Buy-side financial due diligence is an independent review of a target company's financial information, commissioned by the buyer before an acquisition. It examines the quality of earnings, cash flow, working capital, net debt and financial risks, so the buyer can confirm the price, negotiate terms and avoid paying for problems they did not know about.
It is different from an audit. An audit gives an opinion on historical accounts. Due diligence answers the buyer's commercial questions: what profit is genuinely repeatable, how much cash the business will need after completion, and what liabilities should come off the price.
We work with first-time and repeat SME acquirers, management buyout teams, search funds and investors. Each review is scoped to the target, the deal structure and the decisions you need to make.
When buyers bring us in
Situations where buy-side due diligence pays for itself
Buying your first business
You have agreed heads of terms and need an independent view before committing personal capital or debt.
Acquiring a competitor or supplier
You know the market, but need to test whether the target's numbers support the price and your integration plan.
Management buyout
The management team is buying and needs to understand maintainable earnings and how much debt the business can carry.
Search fund or investor acquisition
Your investors expect evidence-based findings on earnings quality, cash conversion and downside risk.
Lender or investor requirement
A bank or backer wants financial diligence before releasing acquisition funding.
Something does not add up
Profit looks strong but cash looks weak, or the seller's figures change between versions. You need answers before exclusivity runs out.
What's included
Understand the business. Challenge the price.
Your proposal sets out exactly what is included, what is excluded and what you receive. Most reviews cover some or all of the following.
Quality of earnings
Test how sustainable reported profit is, adjusting for one-off income, exceptional costs, owner remuneration and accounting judgements.
Revenue and margin analysis
Examine revenue mix, customer concentration, recurring income and margin trends, and where performance relies on a few customers or assumptions.
Working capital and cash conversion
Analyse debtors, creditors, stock and seasonality, and the gap between profit and cash. Establish a normal level of working capital for the deal.
Net debt and debt-like items
Review borrowings, cash and exposures such as deferred income, tax liabilities, director loans and leases that may reduce the equity value.
Forecasts and downside scenarios
Challenge forecast assumptions against historical trading and funding needs, and make the key sensitivities visible.
Decision and negotiation support
Turn findings into price adjustments, warranty and indemnity points, and questions for the seller. We coordinate with your legal and tax advisers.
What we look for
Common financial red flags in SME acquisitions
These issues come up repeatedly in UK SME deals. Each one can change the price, the structure or whether you proceed at all.
- Overstated adjustments to EBITDA"One-off" costs that recur every year, or owner costs added back without evidence.
- Customer concentrationA large share of revenue from one or two customers, often without long-term contracts.
- Working capital squeezed before saleDebtors chased hard and suppliers paid late to flatter cash at completion.
- Revenue recognised too earlyIncome booked before it is earned, particularly on projects, subscriptions and deposits.
- Hidden debt-like itemsUnpaid tax, HMRC time-to-pay arrangements, deferred income, director loans or overdue creditors.
- Weak financial recordsManagement accounts that do not reconcile to the statutory accounts, bank or VAT returns.
- Margins that do not hold upGross margin propped up by stock valuation, capitalised costs or unusual period-end entries.
- Forecasts that ignore historyHockey-stick growth with no evidence from pipeline, contracts or past trading.
Choosing the right review
Buy-side due diligence vs vendor due diligence vs audit
Each serves a different purpose. Buyers often receive vendor reports or audited accounts and wrongly assume no further work is needed.
| Buy-side financial DD | Red-flag review | Vendor DD | Statutory audit | |
|---|---|---|---|---|
| Commissioned by | The buyer | The buyer | The seller | The company |
| Purpose | Inform price, terms and the decision to proceed | Spot deal-breakers early | Prepare the business for sale and speed up the process | Opinion on historical accounts |
| Depth | Tailored, detailed review | Narrow and fast | Broad, seller-led | Compliance-focused |
| Looks forward? | Yes: forecasts, cash needs and downside | Limited | Often | No |
| Best for | Buyers moving towards completion | Buyers deciding whether to proceed | Sellers preparing an exit | Annual reporting |
Selling a business instead? See our due diligence preparation service for sellers.
Start with the right question
Match the review to your decision
Choose the situation closest to yours. Final scope and timing are agreed after a first conversation.
Prioritise headline earnings, cash conversion, customer concentration and major information gaps. A red-flag review is narrower than full financial due diligence, and we will be clear about what it does not cover.
A financial review covering quality of earnings, working capital, net debt and forecasts, with a clear information request list and a findings discussion before you negotiate final terms.
Focus on maintainable earnings, funding capacity and downside headroom, alongside the financial risks and assumptions that matter to lenders backing the buyout.
Discuss the right scope for your dealHow we work
From first conversation to a clear next move
Define the decision
Agree the target, deal stage, access to information, timetable and who will rely on the report.
Request and analyse
Issue a tailored information request, review the records, test key reconciliations and question management.
Surface the findings
Flag material issues as they emerge, separating evidence from open questions, so nothing lands as a surprise.
Support your next move
Deliver the agreed report and talk through what it means for price, funding, completion mechanics and further diligence.
Experience behind the analysis
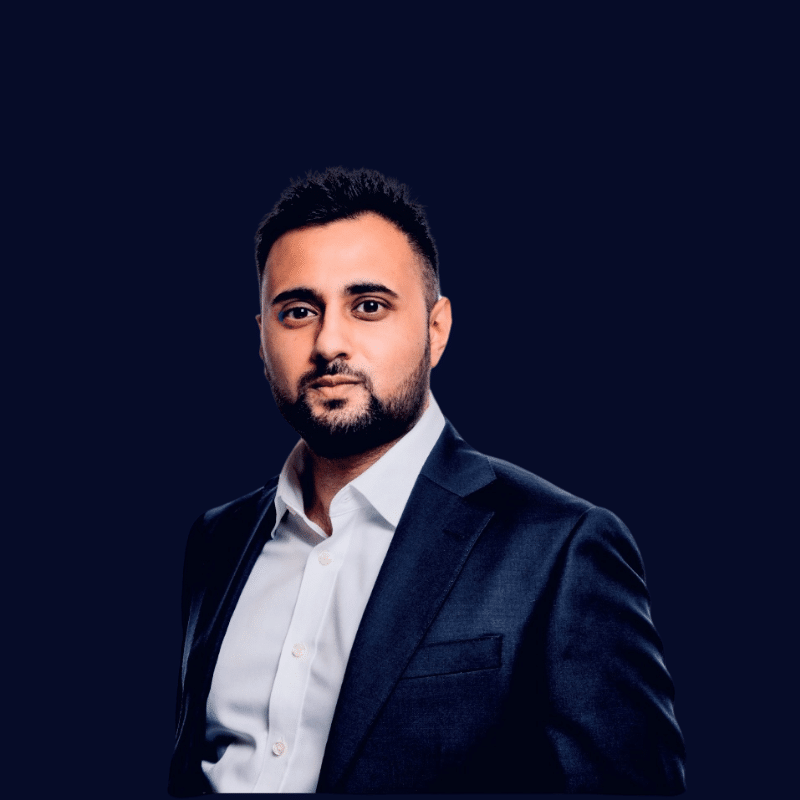
Work directly with Kishen Patel ACA
You deal with the person doing the analysis, not a junior team.
Kish is an ICAEW Chartered Accountant whose background spans Big Four audit, investment banking and corporate advisory. He founded Consult EFC to bring that standard of financial analysis to UK founders, SME acquirers and management teams.
Every engagement starts with the question you need answered, not a generic checklist. We agree the scope, explain our assumptions and make the findings usable in negotiation.
Book a free 30-minute callYour questions, answered
Buy-side due diligence FAQs
Need a more specific answer? Tell us about your situation.
What is the difference between buy-side and vendor due diligence?
Buy-side financial due diligence is commissioned by the buyer to support its acquisition decision, while vendor due diligence is commissioned by the seller. A vendor report can be useful, but it is prepared for the seller's process. Buyers should consider whether independent work is needed for their transaction.
Is financial due diligence the same as an audit?
No. An audit gives an opinion on historical accounts, while financial due diligence answers the buyer's transaction questions. Due diligence focuses on maintainable earnings, cash needs and debt-like items. It does not provide an audit opinion or guarantee that every issue will be found.
When should I commission buy-side due diligence?
Usually after heads of terms are agreed and before you sign the sale and purchase agreement. Starting early in the exclusivity period leaves time to act on findings, renegotiate if needed and coordinate with your legal and tax advisers.
Do I need financial due diligence for a small acquisition?
Smaller deals often carry more risk, not less, because records are less formal and the business depends heavily on the owner. A focused review scoped to the size of the deal can be proportionate and still protect you from the most costly issues.
What documents will you need?
Typically management accounts, statutory accounts, forecasts, bank and debt information, customer revenue data, debtor and creditor ageing, and stock records. The request list is tailored to the target and the agreed scope.
Can you provide a limited red-flag review?
Yes. A focused red-flag review can be scoped where an early decision is needed. It is narrower than full financial due diligence and may leave important areas unexamined, so we set out its limitations clearly in writing.
How long does buy-side due diligence take?
Timing depends on scope, the target's complexity, the quality of its records, management availability and your deadline. We agree a realistic timetable at the start and tell you promptly if missing information affects delivery.
How much does buy-side financial due diligence cost?
Fees depend on the target, the depth of review, data quality and timetable, and are agreed in writing before work begins. We set out the scope, exclusions, deliverables and fee upfront rather than quoting a generic price without understanding the deal.
Does the service include legal, tax or commercial due diligence?
Not unless specifically agreed under a separate scope. Financial due diligence should be coordinated with legal, tax, commercial and other specialist reviews where needed, and we work alongside your other advisers.
Can a lender or another party rely on the report?
Only if agreed in the engagement terms. Intended recipients and reliance arrangements are set out in writing, and a report should not be assumed to be suitable for a lender or third party without that agreement.
Let's talk through the numbers
Tell us about the acquisition
Outline the target, deal stage and timing. Please do not send confidential documents at this stage. We will come back with the right next step.
Scope, exclusions, intended recipients and reliance are agreed in writing. A financial review does not replace legal, tax or other specialist due diligence.