You are likely Series A ready if you can show roughly $1M–$2.5M in ARR, growth of 7%–15% month over month, net dollar retention above 100% and a CAC payback under 12 months. Investors read growth, retention and efficiency together. Your next step is to prepare cohorted data and a runway model covering 24–30 months.
TL;DR:
- Define ARR consistently, exclude one time services revenue, and reconcile deck figures to billing records, CRM exports, and bank sources before diligence.
- Separate retention cohorts by customer segment, acquisition channel, and start month; split churn into voluntary and involuntary, then document each cancellation reason.
- Report CAC, conversion, sales cycle, and early retention by acquisition source; prove one channel repeats economically while a second remains in testing.
- Build base, downside, and upside forecasts from pipeline conversion, sales capacity, cohort expansion, and segment churn, and tie each funding use to dated milestones.
Table of Contents
- Which Series A metrics do investors check first?
- Which pre-Series A milestones sit behind the numbers?
- How do investors test your data and story?
- How much runway and diligence preparation do you need?
- What changes after a successful Series A?
- Which customer acquisition channels help your Series A metrics most?
- How should you segment churn in your Series A data?
- How do you benchmark your SaaS company against others by sector and stage?
- How should you track and forecast MRR growth?
- Why do sales efficiency and sales cycle length matter at Series A?
- What mistakes do founders make when preparing Series A metrics?
- How can fractional CFO support get you ready for Series A?
- FAQ
- Sources
Which Series A metrics do investors check first?
The headline numbers are simple. The proof behind them is not. Here is what each metric means and the range investors tend to expect.
ARR. Many Series A SaaS companies sit between $1M and $2.5M ARR. Treat that as a common band, not a gate. A hot market or an exceptional team can raise below it, and a slower-growing business may need to sit above it. Define ARR once, exclude one-off services revenue and keep the definition identical in every document you send.
Growth. The same SaaStr benchmark puts expected growth at 7%–15% month over month in earlier-stage contexts. “Believable path” matters more than the peak month. Investors want to see growth that continues for several consecutive months and a pipeline that explains why it will carry on.
Retention. Net dollar retention (NDR) is revenue from existing customers today, including expansion, divided by what they paid a year ago. Gross retention strips out expansion and shows how much revenue leaks. An NDR of 100% or more is a core signal because it means the installed base grows even with no new sales. Expansion revenue also lowers your blended acquisition cost over time.
CAC payback and Magic Number. CAC payback is the months of gross-margin-adjusted revenue needed to recover what you spent winning a customer. The target is under 12 months. Magic Number compares net new ARR in a period with the sales and marketing spend of the prior period, and a figure of about 1 or above suggests spend is converting well. Show both by channel, not only blended.
Burn multiple. Divide net burn by net new ARR. Investors scrutinise burn multiple and CAC payback as heavily as growth, and a burn multiple of 1–2x is the aim. Anything higher signals reliance on outside capital to keep growing.
Unit economics and gross margin. Cloud businesses typically run gross margins of 65%–80% depending on scale. Present gross margin with hosting, support and customer success costs clearly allocated, then show contribution margin per segment so investors can see where the economics hold.
- Define every metric in a single page and reuse it everywhere.
- Show ARR, NDR and CAC payback side by side over time.
- Pair each number with the cohort or channel that explains it.
A longer CAC payback is not fatal, but it must be justified by something stronger elsewhere, such as exceptional net dollar retention or high growth velocity.
Pro Tip: Put the triad of revenue, retention and runway on one slide, because investors expect that combination and a clear path to improving unit economics.
For deeper definitions, our guide to CAC, LTV and burn multiple walks through the calculations step by step.
Which pre-Series A milestones sit behind the numbers?
Metrics tell investors what happened. Milestones tell them why it will keep happening.
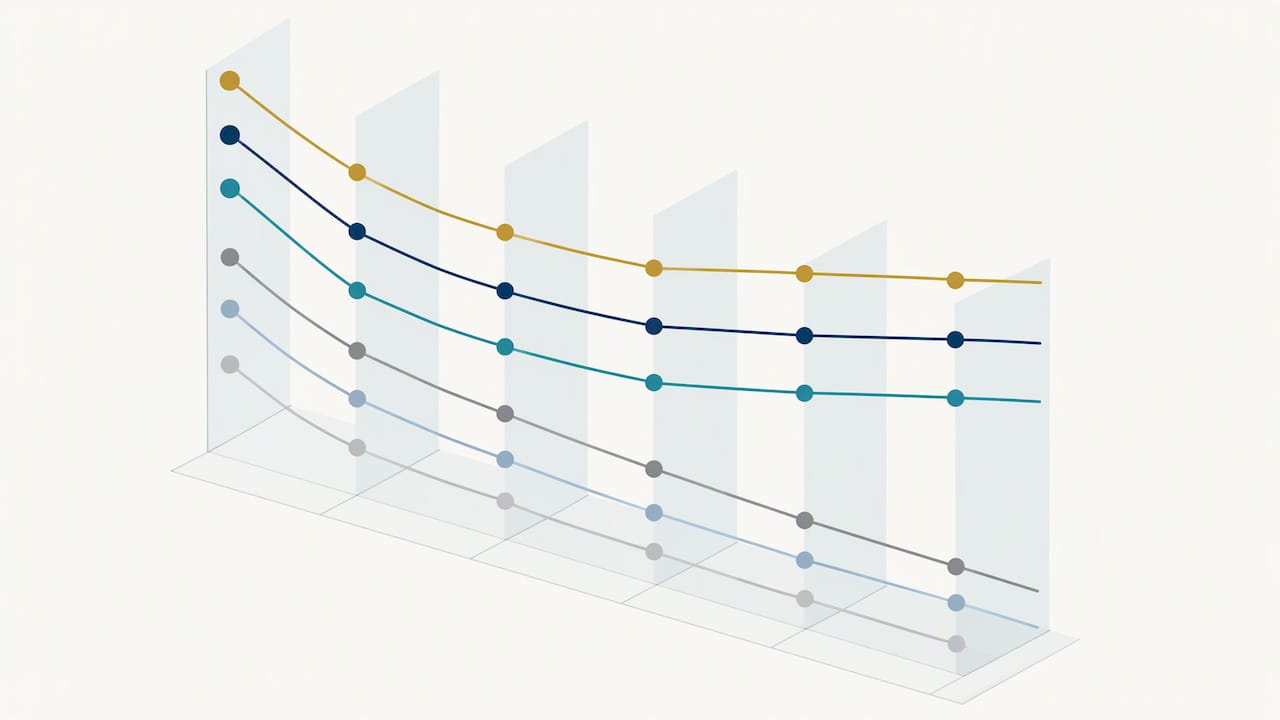
Product–market fit. The best evidence is behavioural. Retention cohorts that flatten rather than decay, a healthy conversion from trial to paid, and usage that deepens over time all point to a product people rely on. Show these as cohort charts, not anecdotes.
A repeatable acquisition channel. One channel that produces predictable pipeline matters more than five that work occasionally. Investors look at lead velocity rate (LVR), the month-on-month growth in qualified leads, because it moves before revenue does. Improving LVR with stable conversion rates is a strong signal.
The team. By Series A, investors expect more than founders and a few engineers. They look for an accountable sales lead or someone who owns revenue, a product owner who runs a real roadmap, and finance capability that produces trustworthy monthly numbers. You do not need every hire in place, but you need a credible plan for each gap.
The roadmap and the ask. A plan tied to milestones makes the funding request concrete. Show what the money buys, which targets it unlocks and how those targets lead to the next round.
- Cohort retention curves that stabilise.
- One acquisition channel with documented, repeatable conversion.
- Named owners for sales, product and finance.
- A funding ask mapped to dated milestones.
How do investors test your data and story?
Investors rarely doubt that you can grow. They doubt the numbers you present. Growth is still the top factor, but data integrity is now a key differentiator, and clean, segment-specific reporting signals a professional, scalable operation.
The most common error is reporting blended averages across disparate customer segments. A blended churn figure can hide a leaky SMB tier behind a healthy enterprise base. Split cohorts by segment, acquisition channel and start month, and the churn hotspots and growth drivers become visible.
Here is what a diligent investor looks for, in rough order:
- Consistent definitions. The ARR in your deck, your model and your billing system should reconcile. Document the exclusions.
- Traceable sources. Every headline figure maps to a system of record, whether billing, CRM or bank.
- Leading indicators. LVR, pipeline coverage, stage-to-stage conversion and CAC by channel show whether next quarter is already secured.
- Explained churn. Each lost cohort has a reason you can evidence.
The usual red flags are inconsistent definitions between documents, unexplained churn and a forecast with no pipeline behind it. Each is fixable: align definitions, tag churn reasons in your CRM and show weighted pipeline against the plan.
Pro Tip: Build one reconciliation sheet that ties deck figures to source exports before you share anything. It is the fastest way to remove doubt.
Our investor-ready reporting guide shows the dashboard formats investors expect, and our overview of what diligence teams probe explains the evidence behind each metric.
How much runway and diligence preparation do you need?
Plan for longer than you think. The median interval between Seed and Series A has stretched to roughly 20–25 months, and the market has shifted toward quality over quantity, with fewer rounds closing. Planning 24–30 months of runway gives you room to run a proper process and absorb a delay without negotiating from weakness.
Preparing the data room early shortens the process. Our Series A financial readiness checklist covers the full list, and our runway planning guide explains how to model it.
- An investor-ready financial model with base, best and worst scenarios.
- Cohort tables for retention and revenue.
- CAC by channel, with the method stated.
- Sample customer contracts and clean billing exports.
- A clear cap table.
Scenario models should show how capital would be allocated under each case, so investors see you have thought about what happens if growth runs ahead of plan or behind it.
When a weakness exists, show the trend rather than an excuse. A payback period that has improved over time, with the cause identified, is more persuasive than a defensive explanation.
| Preparation area | What to show | Why it matters |
|---|---|---|
| Runway | 24–30 months under the base case | Absorbs a longer raise |
| Financial model | Three scenarios with allocation | Shows planning discipline |
| Cohorts | Segment-level retention | Removes blended-average doubt |
| Channel CAC | Spend and payback per channel | Proves repeatability |
What changes after a successful Series A?
Closing is the start of a tougher reporting cycle. Investors judge how you deploy capital, particularly the trade-off between pushing growth and protecting efficiency.
The metrics under the closest scrutiny afterwards are the ones you pitched on:
- ARR growth against the plan you presented.
- Net dollar retention across cohorts.
- CAC payback by channel.
- Burn multiple against the 1–2x range.
Timing to the next round depends on performance, not the calendar. The bar rises again at Series B, where the same triad of revenue, retention and runway applies at a larger scale. A company that hits its milestones early can raise sooner, and one that misses them should expect longer. Carta’s data also shows capital concentrating in fewer, higher-quality rounds, which makes disciplined reporting more valuable still.
Which customer acquisition channels help your Series A metrics most?
Investors do not only ask how much you grew. They ask which channel produced it and whether it can be repeated. A channel analysis breaks CAC, conversion rate, sales cycle and early retention down by source: outbound, inbound content, partnerships, paid and product-led sign-ups.
The pattern investors want is a channel that grows with spend without CAC rising sharply. Blended CAC can look healthy while one channel quietly subsidises another, so report each source separately and show the trend over several months. Also compare retention by channel, because customers acquired cheaply through one source sometimes churn faster, which erodes the payback you calculated.
Outbound deserves particular care. Reply rates, meeting rates and pipeline conversion should be measured at each step. Practical advice on B2B SaaS lead generation can help you tighten the top of the funnel, and any improvement should show up in LVR and CAC efficiency in your numbers.
The strongest story is one dominant channel with proven economics and a second in early testing. That shows repeatability today and a path to diversification, which is exactly what a Series A investor is underwriting.
How should you segment churn in your Series A data?
A single churn figure invites questions you cannot answer. Split it into voluntary and involuntary churn, then by segment.
Voluntary churn is a customer deciding to leave: the product did not fit, a competitor won, budgets were cut. It points to product, onboarding or positioning problems, so tag the reason on every cancellation. Involuntary churn is a failed card, an expired payment method or a billing error. It is not a verdict on your product, and it is often the cheapest churn to fix through retry logic, card-update reminders and dunning emails.
Separating them changes the story. A business with 3% monthly churn, most of it involuntary, has a billing problem that a few weeks of work can reduce. The same headline with mostly voluntary churn has a product problem that takes longer to solve.
Then cut each type by customer size, plan and start cohort. As investors note, blended metrics mask churn hotspots. For product-led teams, app retention benchmarks give a useful reference for what healthy usage retention looks like. Show your fixes alongside the figures so churn reads as a managed number, not a mystery.
How do you benchmark your SaaS company against others by sector and stage?
Benchmarks are only useful when you compare like with like. A vertical SaaS product selling to regulated mid-market firms will not match a self-serve developer tool on sales cycle, ACV or gross margin. Choose a peer set by sector, customer size and go-to-market motion, then compare at the same stage.
Several sources help. Carta’s Series A benchmarking tools provide median deal-size and valuation tables drawn from tens of thousands of rounds, and its fundraising benchmarks give median Series A metrics and dilution ranges. Treat medians as guides, not targets, because individual deals vary widely with market conditions and team quality. For operating efficiency, the BVP benchmarking report is useful for gross margin ranges and efficiency measures. Our 2026 SaaS financial benchmarks tabulate gross margin, CAC payback and churn.
When you fall short of a benchmark, say so before the investor does, then explain what the shortfall reflects. A longer sales cycle may be the price of larger contracts, which is a legitimate trade if retention and ACV support it. Presenting your position against a defined peer set shows self-awareness, and it keeps the conversation on your trajectory.
How should you track and forecast MRR growth?
MRR is the clearest view of momentum, and investors read its components, not only the total. Break monthly movement into new MRR, expansion, contraction and churned MRR. A bridge that shows all four explains whether growth comes from new logos, existing customers or both, and whether leakage is rising.
Growth rates should be read as a pattern. Steady compounding at a modest rate is more convincing than one spike followed by a flat quarter. Where growth has slowed, show why and what changed.
For forecasting, avoid a single top-down growth percentage applied across twelve months. Build the forecast from drivers: pipeline by stage with historical conversion, sales cycle length, rep capacity and ramp time, expansion rates by cohort and churn by segment. Then run three cases. The base case uses observed conversion rates, the downside lowers conversion and extends the sales cycle, and the upside reflects only changes you have already evidence for.
Check the forecast against actuals every month and explain variances. A model whose errors you can account for earns trust, and one that is never revisited loses it. Our investor-grade financial modelling work builds exactly this kind of driver-based forecast.
Why do sales efficiency and sales cycle length matter at Series A?
Sales efficiency tells investors how much new ARR each pound or dollar of sales and marketing spend produces. Magic Number and CAC payback are the usual measures, and both feed directly into the burn multiple scrutiny investors apply. A reasonably short CAC payback is the ideal benchmark, and a longer one has to be offset by exceptional retention or growth velocity.
Sales cycle length drives efficiency in a less obvious way. A long cycle ties up cash, delays revenue recognition against spend and makes forecasts harder to trust. Investors compare cycle length with deal size: a longer cycle on large contracts can be perfectly sound, while the same cycle on small deals may signal a process problem.
Measure the cycle by segment and by stage, and track how it moves as you add reps. If new hires take longer to close than founders do, investors will read that as a sign the process is not yet repeatable. Show ramp time, quota attainment and win rate alongside the cycle, so the picture covers the whole sales motion.
Shortening the cycle is often a data exercise first. Find the stage where deals stall, then fix qualification, pricing clarity or the buying-committee approach there.
What mistakes do founders make when preparing Series A metrics?
The same three errors turn up repeatedly: blended metrics that hide segment problems, cohorts that are missing or cut inconsistently, and runway planned to the minimum rather than with a buffer. The fixes are unglamorous and effective: standardised definitions, a financial model built to investor standards and a short KPI dashboard that shows only what the pitch relies on. A fractional CFO delivers this discipline without a full-time salary, and it usually shortens the path to a clean data room.
— Kishen Patel
How can fractional CFO support get you ready for Series A?
We help founders turn raw numbers into evidence investors trust. Our services most relevant to a Series A raise are:
- Fractional CFO services for ongoing financial leadership and reporting discipline.
- Investor-grade financial modelling for scenario-based, pitch-ready forecasts.
- Due diligence preparation to organise the documents and data room investors will request.
We support founders with financial reporting and modelling. Our team is led by ICAEW Chartered Accountant Kishen Patel, bringing Big Four-style rigour without the cost of a permanent hire.
To see how we would work with your business, start with our fractional CFO services page and get in touch to talk through your timeline.
FAQ
What ARR do you need to raise a Series A?
Many SaaS companies raise between $1M and $2.5M ARR. It is a common range, not a rule, and strong growth, retention and efficiency can offset a lower figure.
What growth rate do Series A investors expect?
Growth of 7%–15% month over month is often expected in earlier-stage contexts. Investors care most that the rate is sustained and backed by pipeline you can evidence.
What is a good burn multiple for Series A?
Aim for a burn multiple of 1–2x. Anything higher suggests growth depends on constant outside funding rather than efficient spend.
How long does it take to get from seed to Series A?
The median interval is around 20–25 months. Plan your runway and your fundraising timetable accordingly.
Why do investors want cohort data instead of blended averages?
Blended averages combine very different customer segments and can hide churn hotspots. Segment-specific cohorts show where growth really comes from and where revenue leaks.
Recommended
- SaaS Cohort Analysis for Better Customer Retention in 2026
- SaaS Cohort Analysis 2026: Retention, Expansion, Payback
- Investor-Ready SaaS Metrics 2026: The Founder’s Reporting Guide
This article is for general information only and is not professional advice.
Not sure where your business stands right now?
Book a free 30-minute call with Kish. Bring your numbers, your questions, or just your situation. You will leave with a clearer picture than you arrived with.
Book a Free Strategy Call
Over 12 years across Big Four audit, Investment Banking, and corporate advisory. Kish works with SaaS founders, tech companies, and ambitious UK SMEs from £1M to £50M in revenue on fundraising, valuations, exit planning, and financial strategy. ICAEW regulated. Big Four trained. Based in London.